
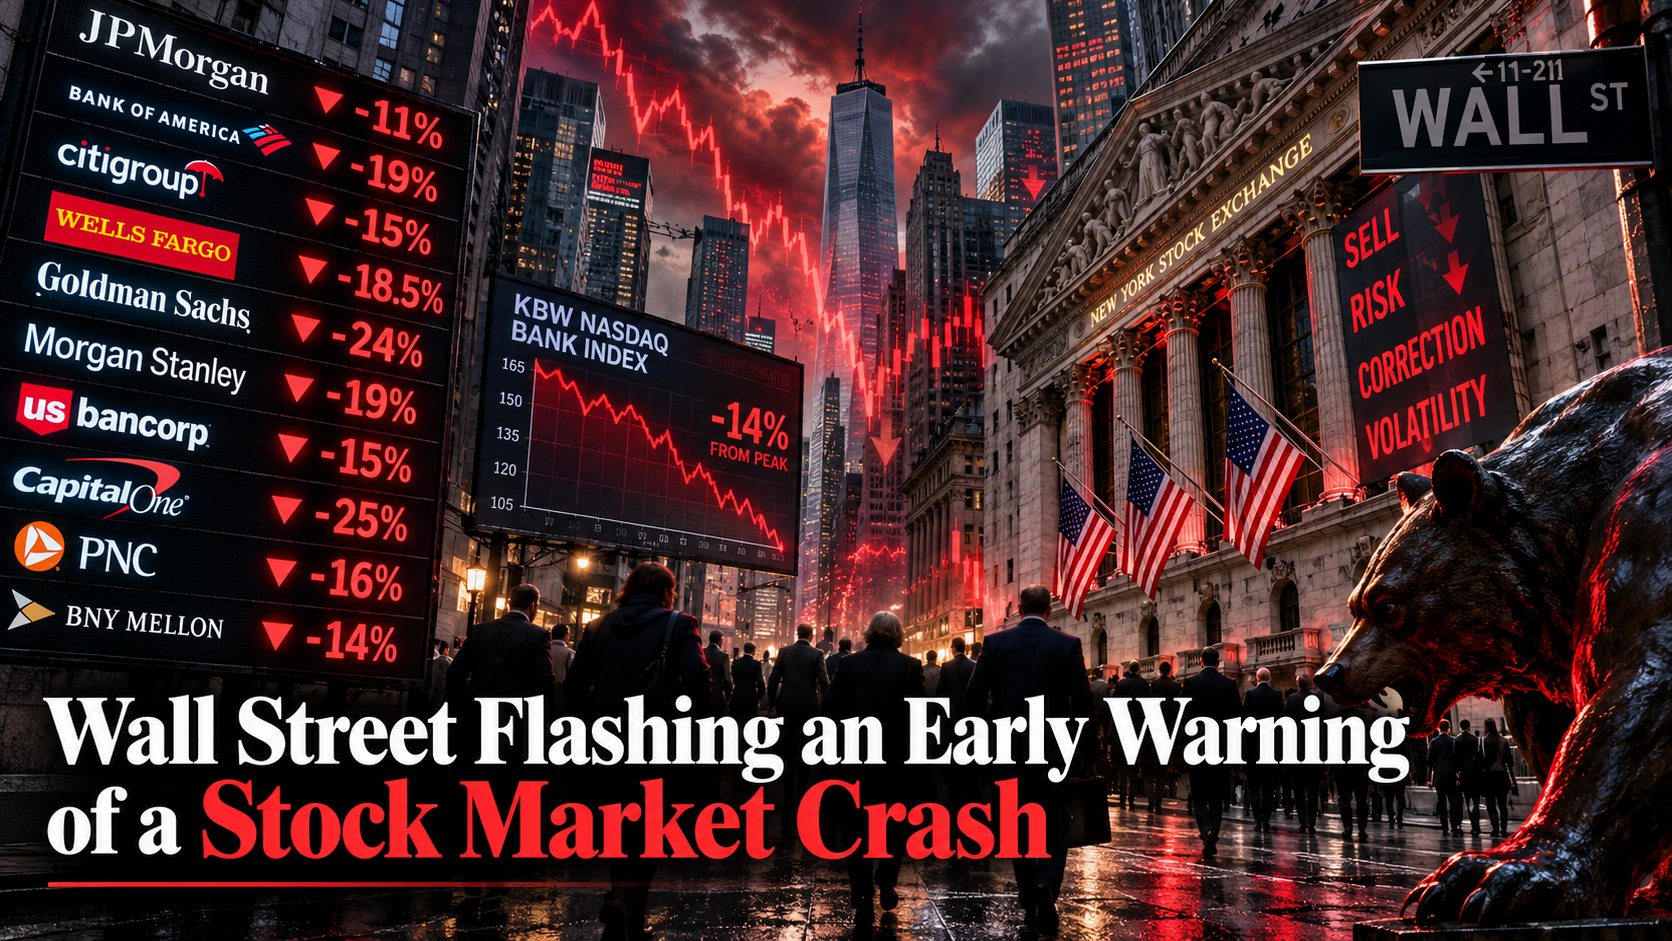
The largest banks in the United States are sending a warning that investors cannot afford to ignore. While the S&P 500 remains near record highs, America’s most influential financial institutions are experiencing significant share-price declines, raising an uncomfortable question: Is the banking sector anticipating a broader stock market correction?
From JPMorgan Chase to Goldman Sachs, Bank of America to Morgan Stanley, some of Wall Street’s most recognizable names have fallen sharply from their recent highs.
More troubling is the behavior of the KBW Nasdaq Bank Index, a closely watched benchmark of American banking shares, which has declined approximately 13%–14% from its August peak.
According to Reuters reporting on October 8, the index had fallen approximately 13% since August, reflecting growing concerns about higher Treasury yields, funding costs and the outlook for bank profitability.
The divergence between banking stocks and the broader equity market deserves particular attention because financial institutions have historically provided important clues about changing economic conditions.
The Banking Selloff: Ten Major Institutions Under Pressure
The scale of the reported declines illustrates just how widespread the weakness has become.
The following figures represent a market snapshot supplied to Invest Offshore. Individual declines are indicative and have not been independently confirmed against a common closing date and peak-price methodology.
| U.S. Financial Institution | Reported decline |
|---|---|
| JPMorgan Chase | -11% |
| Bank of America | -19% |
| Citigroup | -15% |
| Wells Fargo | -18.5% |
| Goldman Sachs | -24% |
| Morgan Stanley | -19% |
| U.S. Bancorp | -15% |
| Capital One | -25% |
| PNC Financial Services | -16% |
| BNY Mellon | -14% |
Two institutions stand out: Capital One, reportedly down 25%, and Goldman Sachs, reportedly down 24%.
A correction is conventionally defined as a decline of 10% or more from a recent high, while a bear market generally begins at a decline of 20%.
By that measure, all ten institutions in the reported snapshot have entered correction territory, with Goldman Sachs and Capital One experiencing declines consistent with bear-market territory.
However, falling bank shares do not automatically mean the banking system is insolvent or facing an imminent crisis. Equity prices also reflect interest-rate expectations, changes in future earnings estimates and investor risk appetite.
Nevertheless, when weakness becomes this widespread across the financial sector, it is worth asking what the market may be anticipating.
The KBW Nasdaq Bank Index: A Potential Canary in the Coal Mine

The KBW Nasdaq Bank Index (BKX) tracks 24 publicly traded American banking stocks, including major national banks, regional institutions and thrifts.
Unlike broader equity benchmarks, banking indexes offer investors a concentrated view of institutions operating at the center of the credit system.
Banks are exposed to virtually every major component of economic activity:
- Consumer borrowing and credit card spending.
- Residential and commercial real estate financing.
- Corporate lending and business investment.
- Government debt and Treasury securities.
- Capital markets, mergers and acquisitions.
- Deposit flows, liquidity and funding conditions.
When banking shares weaken, investors may be reacting to deteriorating expectations across several of these markets simultaneously.
The October decline is especially noteworthy because the wider stock market has shown considerable resilience.
On October 5, the S&P 500 closed at 7,773.95, within approximately 0.3% of its previous record, while the Nasdaq Composite reached a new high.
The question is whether major technology companies and other market leaders can continue supporting broad indexes while financial institutions lose momentum.
A stock market reaching new highs while banks are falling is not necessarily a healthy market. It may be a market becoming increasingly dependent on a narrower group of companies.
History’s Warning: 2000, 2008 and 2020
One of the most intriguing arguments surrounding the latest banking correction concerns the historical relationship between bank stocks and the S&P 500.
During previous market disruptions, banking shares have sometimes weakened ahead of the broader market.
2000: The Dot-Com Bubble
The technology bubble of 2000 demonstrated how extraordinary stock market valuations could become detached from economic fundamentals.
As speculative technology shares surged, vulnerabilities developed elsewhere in financial markets.
When the bubble burst, investors discovered that record equity prices offered little protection against deteriorating earnings expectations and tightening financial conditions.
The lesson was straightforward: strength in headline indexes can conceal weakness beneath the surface.
2008: The Global Financial Crisis
The 2008 financial crisis provides a particularly powerful example of why banking-sector performance matters.
Mortgage-related securities, excessive leverage, deteriorating credit quality and interconnected financial exposures placed enormous pressure on major institutions.
Banking stocks weakened significantly as investors began recognizing problems that would eventually destabilize the global financial system.
The collapse of Lehman Brothers in September 2008 accelerated a crisis already developing across credit markets.
Unlike the technology-driven downturn of 2000, the 2008 crisis originated directly within the financial system.
This distinction matters because banks do more than participate in the economy: they provide the credit infrastructure upon which economic activity depends.
2020: The Pandemic Market Crash
The coronavirus pandemic produced one of the fastest equity-market collapses in modern history.
Financial institutions suffered as investors anticipated economic shutdowns, loan losses and extraordinary monetary interventions.
Banking-sector weakness accompanied the rapid deterioration in broader market expectations.
However, the 2020 episode also demonstrates the limitations of relying on banking shares as a predictive indicator. The pandemic shock was exceptionally rapid, and the timing of the banking-index peak relative to the S&P 500 does not establish a consistent four-to-eight-month lead.
Does the Banking Index Really Lead the S&P 500 by Four to Eight Months?
Some market commentary argues that the KBW Bank Index peaked four to eight months before the S&P 500 in the major market downturns of 2000, 2008 and 2020.
That precise historical relationship should be treated as a hypothesis rather than an established forecasting rule. The result depends on the peaks selected, the measurement period and whether subsequent market declines are measured from daily closes or intraday highs.
What is more defensible is the broader observation that financial-sector weakness can reveal deteriorating credit and liquidity conditions before they become obvious in headline equity benchmarks.
History gives investors a reason to monitor banking shares closely, but it does not provide a reliable countdown to the next crash.
Why Are America’s Largest Banks Falling?
Several important financial forces may be contributing to the current banking correction.
1. Rising Treasury Yields and Bond Market Pressure
Banks own substantial portfolios of fixed-income securities, including U.S. government bonds and mortgage-backed securities.
When bond yields rise, the market value of existing fixed-rate securities generally declines.
This can create unrealized losses and pressure capital flexibility, depending on how securities are classified, funded and hedged.
Higher Treasury yields can also increase banks’ funding costs and make borrowing more expensive for households and businesses.
In October 2026, the U.S. 10-year Treasury yield has moved above 5%, increasing scrutiny of interest-rate-sensitive businesses and assets.
2. Increasing Competition for Deposits
Banks traditionally earn profits by lending money at higher rates than they pay to depositors.
When interest rates rise, customers increasingly demand competitive returns on their cash.
Money market funds, Treasury bills and alternative financial platforms can attract deposits that might otherwise remain in conventional bank accounts.
To retain funding, banks may need to increase deposit rates, potentially compressing net interest margins.
3. Commercial Real Estate and Credit Risk
Commercial real estate remains an important area for monitoring financial-sector exposure.
Office buildings, refinancing requirements and debt servicing costs can become more challenging when interest rates remain elevated.
Regional and national banks have different exposure profiles, but a prolonged period of expensive financing can pressure borrowers throughout the economy.
Higher rates can also affect credit cards, auto loans, small-business lending and residential mortgages.
4. Investment Banking and Capital Markets Activity
Institutions such as Goldman Sachs and Morgan Stanley depend substantially on activities beyond conventional deposit-taking and lending.
Trading, underwriting, mergers, acquisitions and investment management contribute to their earnings.
When companies postpone acquisitions or public offerings, investment banking revenues can weaken.
However, this relationship is not uniform. Periods of market volatility can also create profitable trading opportunities.
5. Concerns About the Economic Outlook
Bank shares are particularly sensitive to expectations about future economic activity.
If investors expect slowing employment, weakening consumer demand or rising defaults, they may reduce the prices they are willing to pay for bank earnings.
This means a banking correction can reflect changing expectations even before those changes appear clearly in economic statistics.
The S&P 500’s Hidden Vulnerability: Market Concentration
One of the most important developments in American equity markets is the growing influence of a relatively small group of technology companies.
Artificial intelligence, semiconductor investment, cloud computing and digital infrastructure have attracted enormous amounts of institutional capital.
Companies associated with these industries can exert a disproportionate influence on capitalization-weighted indexes such as the S&P 500.
Consequently, headline index performance may remain strong even when a substantial number of constituent companies are falling.
Recent market analysis has highlighted this concentration problem, with the median S&P 500 stock trading significantly below its own recent high despite the index remaining near record territory.
This creates an important distinction between the performance of the stock market index and the financial health of the market as a whole.
If banking institutions continue declining while technology shares advance, investors should examine whether the rally is supported by broad earnings growth or increasingly concentrated speculative enthusiasm.
The longer the divergence persists, the more important it becomes to understand what is driving it.
The Coming Bank Earnings Season Could Be Decisive
The next major test arrives almost immediately.
JPMorgan Chase, Citigroup, Goldman Sachs and Wells Fargo are scheduled to report third-quarter results on October 13, followed by Bank of America and Morgan Stanley on October 14.
According to Reuters, analysts anticipate earnings growth of as much as 20% at major U.S. banks, even as investors express concerns about higher yields, credit conditions and funding expenses.
This apparent contradiction is important.
If earnings remain strong while shares fall, the market may be discounting risks that have not yet materially affected reported profits.
Alternatively, investors may simply have overestimated future earnings growth, leaving previously expensive bank valuations vulnerable to adjustment.
Upcoming management commentary could help resolve the uncertainty.
Investors should pay particular attention to loan growth, deposit costs, credit provisions, capital ratios and guidance for the remainder of 2026 and into 2027.
A stabilization in bank shares following strong results could weaken the bearish interpretation.
Conversely, disappointing forward guidance accompanied by further share-price declines would strengthen the case that financial conditions are deteriorating.
What This Means for Offshore Investors
For international investors, the banking correction raises questions extending well beyond Wall Street.
The United States remains central to the global monetary system through its Treasury market, dollar funding networks, banking relationships and capital markets.
Financial stress within major American institutions can affect international liquidity, cross-border lending and the valuation of assets around the world.
Several strategic considerations deserve attention.
Geographic diversification: International investors may wish to review their dependence on U.S. equity markets and financial institutions. Diversification across jurisdictions can reduce certain concentration risks, although it introduces currency, regulatory and counterparty considerations.
Banking counterparty exposure: The legal structure of deposits, custodial relationships and securities ownership matters. A decline in a bank’s share price does not necessarily threaten customer deposits, but institutional credit quality remains an important consideration.
Precious metals: Gold may attract interest during periods of financial uncertainty, particularly among investors seeking assets outside the direct credit obligations of commercial banks. However, gold prices can be volatile and are also influenced by real yields, currency movements and liquidity needs.
Government bonds: U.S. Treasuries remain central to global financial markets, but rising yields can produce substantial mark-to-market losses on longer-duration holdings.
Liquidity management: Investors may place greater emphasis on maintaining accessible reserves rather than relying on forced asset sales during volatile markets.
For Invest Offshore readers, the broader objective is not to predict the exact date of the next market correction. It is to understand where financial risks are concentrated and how those risks might spread across borders and asset classes.
Three Scenarios for the Remainder of 2026
The banking correction presents three plausible paths for financial markets.
Scenario One: Banking Shares Stabilize
Third-quarter earnings exceed expectations, credit conditions remain resilient and deposit costs moderate.
Bank stocks recover, supporting continued economic expansion and improving market breadth.
Under this scenario, the recent correction represents a sector-specific valuation adjustment rather than a warning of a broader equity collapse.
Scenario Two: Financial Divergence Continues
Bank shares remain under pressure while the S&P 500 continues advancing, driven primarily by technology and artificial intelligence investments.
Market concentration increases, and investors begin demanding larger risk premiums from economically sensitive companies.
This scenario may be sustainable temporarily, but it leaves the equity market more vulnerable to disappointment among its largest constituents.
Scenario Three: The Banking Correction Spreads
Higher financing costs, weaker credit growth and deteriorating earnings expectations begin affecting the broader economy.
Investor concerns migrate from banking shares to commercial real estate, consumer finance, industrial companies and eventually the largest technology stocks.
Under this scenario, the banking correction would prove to have been an early manifestation of a broader repricing of risk.
None of these outcomes is inevitable. The important consideration is whether incoming economic and financial evidence begins favoring one scenario over the others.
The Invest Offshore Perspective: Watch the Banks, Not Just the S&P 500
The correction in America’s leading banking shares warrants serious attention.
Financial institutions occupy a unique position within the global economy. They are exposed to borrowing costs, economic growth, asset valuations, credit quality and investor confidence simultaneously.
Their share prices can therefore provide useful information about changes in financial conditions.
Yet the historical evidence must be interpreted carefully.
The fact that bank shares declined before or during previous market crises does not mean every banking correction will produce another crash.
Nor does weakness in Goldman Sachs, JPMorgan Chase or Bank of America necessarily indicate that a systemic banking emergency is developing.
The warning becomes more significant when banking-sector weakness is accompanied by widening credit spreads, accelerating loan losses, deteriorating liquidity, falling market breadth and weaker corporate earnings expectations.
That combination would suggest that selling pressure is no longer confined to the financial sector.
For now, one of the most important questions confronting investors is why American banking shares are struggling while the broader stock market remains so close to record highs.
The greatest danger may not be the banking correction itself. It may be the possibility that investors are overlooking what the banking correction is telling them about the price of money, the availability of credit and the sustainability of today’s elevated asset valuations.
In financial markets, the warning signs do not always arrive at the same time.
Sometimes the banks weaken first.
And sometimes Wall Street only understands the message after the rest of the market begins to follow.
Invest Offshore Editorial Note: Market figures reflect the October 2026 reporting period and the supplied individual bank-performance snapshot. Share-price declines vary by reference date and measurement methodology. This article presents market analysis, not a prediction of an imminent crash or individualized investment advice.
Leave a Reply