
Invest Offshore | October 21, 2026
France dominates Europe’s banking landscape, HSBC loses its crown, and Switzerland’s largest bank faces a decision that could redraw the financial map of Europe.
Europe’s banking hierarchy is undergoing a remarkable transformation. Consolidation, regulatory pressure, changing capital requirements, and the pursuit of international wealth are reshaping the continent’s largest financial institutions.
But perhaps the most consequential development is unfolding in Switzerland, where UBS Group, the country’s remaining global banking giant following its acquisition of Credit Suisse in 2023, is confronting an increasingly difficult question:
Can the world’s leading wealth-management franchise afford to remain headquartered in Switzerland?
Recent reports indicate that UBS is examining contingency plans that could include relocating its headquarters, potentially to London, or pursuing a transformative international banking combination.
For a bank synonymous with Swiss financial stability, such a decision would have repercussions far beyond Zurich.
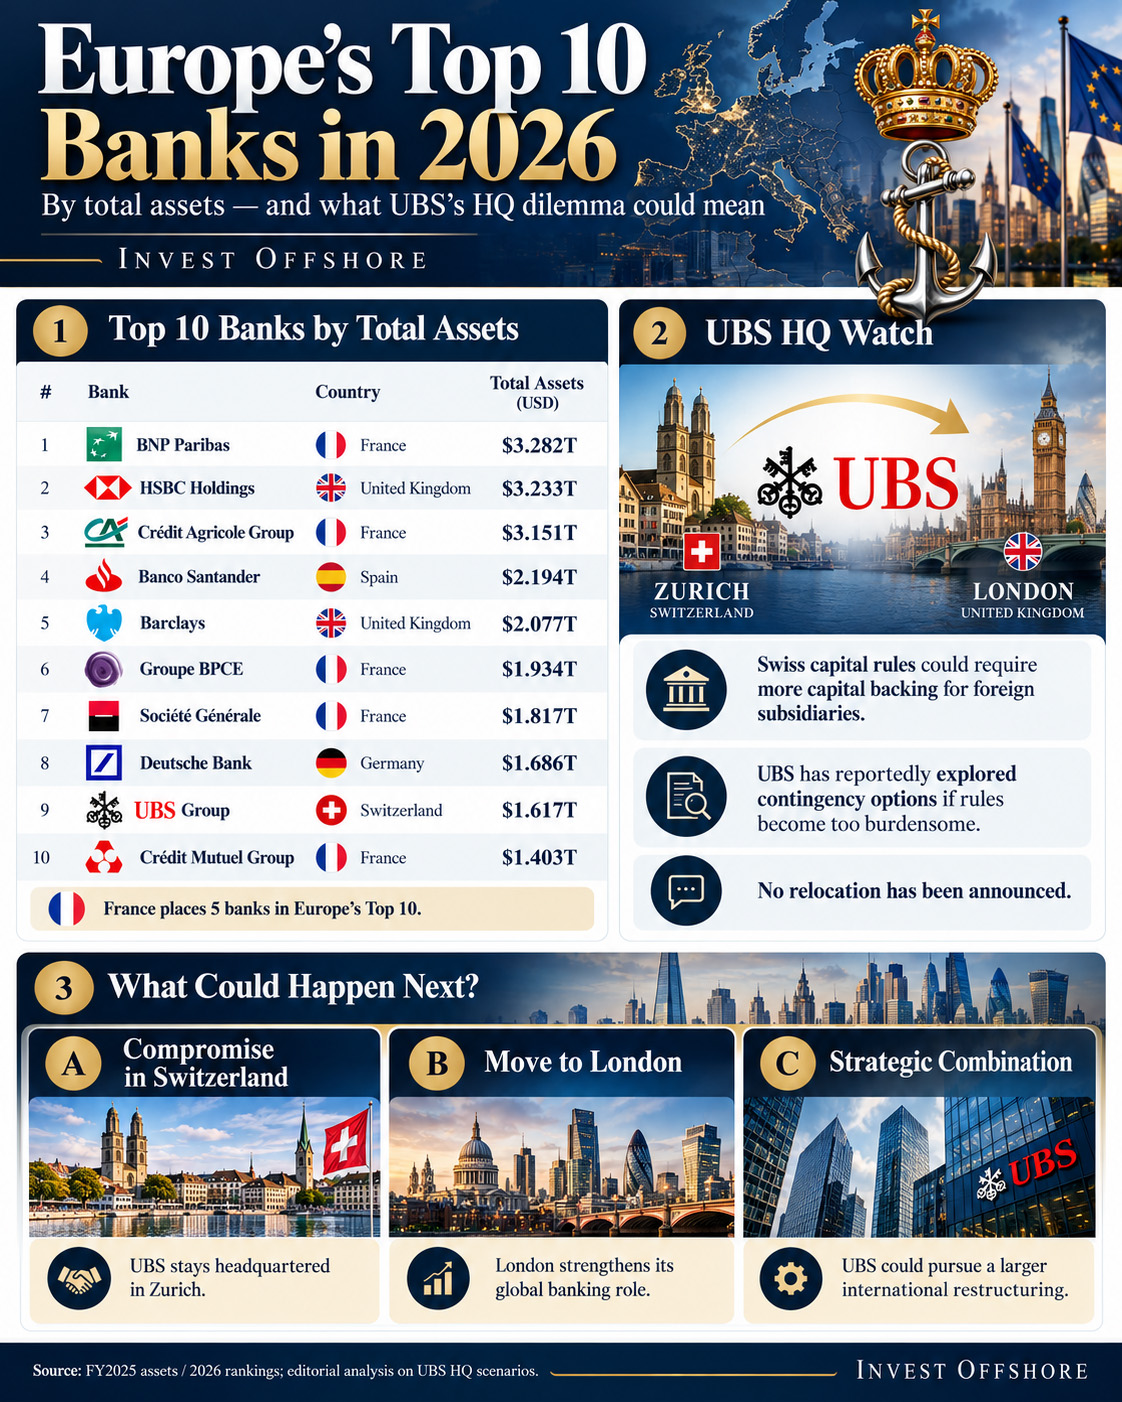
Europe’s Top 10 Banks by Total Assets
According to the 2026 rankings, based on full-year 2025 financial statements, BNP Paribas has overtaken HSBC to become Europe’s largest banking group.
The ranking includes the United Kingdom and Switzerland, not merely European Union member states.
| Rank | Banking Group | Country | Total Assets (USD) |
|---|---|---|---|
| 1 | BNP Paribas | France | $3.282 trillion |
| 2 | HSBC Holdings | United Kingdom | $3.233 trillion |
| 3 | Crédit Agricole Group | France | $3.151 trillion |
| 4 | Banco Santander | Spain | $2.194 trillion |
| 5 | Barclays | United Kingdom | $2.077 trillion |
| 6 | Groupe BPCE | France | $1.934 trillion |
| 7 | Société Générale | France | $1.817 trillion |
| 8 | Deutsche Bank | Germany | $1.686 trillion |
| 9 | UBS Group | Switzerland | $1.617 trillion |
| 10 | Crédit Mutuel Group | France | $1.403 trillion |
Source: The Global Banker, 2026 European rankings, updated October 12, 2026. Figures rounded from reported FY2025 assets converted into US dollars. S&P Global Market Intelligence’s April 2026 ranking independently confirms the same top-ten order; methodologies produce some differences in reported asset totals.
France Has Become Europe’s Banking Powerhouse
Five of Europe’s ten largest banking groups are headquartered in France.
BNP Paribas, Crédit Agricole, Groupe BPCE, Société Générale, and Crédit Mutuel collectively represent more than $11.5 trillion in reported assets.
This concentration illustrates France’s growing institutional importance within European finance.
BNP Paribas has strengthened its wealth-management capabilities through acquisitions, while Crédit Agricole combines an extensive cooperative banking network with international investment banking and asset-management activities.
Meanwhile, HSBC continues its strategic shift toward Asia and the Middle East, Santander is expanding its international banking presence, and Deutsche Bank remains central to Germany’s financial infrastructure.
Europe’s banking industry is increasingly defined by institutions capable of operating across multiple jurisdictions, currencies, and regulatory environments.
That brings us to UBS.
UBS: Europe’s Ninth-Largest Bank, but Potentially Its Most Important Relocation Story
<underline>Switzerland’s banking dilemma began with the collapse of Credit Suisse in March 2023.</underline>
UBS’s emergency acquisition of its historic rival created an institution of enormous importance to the Swiss economy.
Swiss policymakers subsequently concluded that the country’s banking framework needed additional safeguards to protect taxpayers and ensure that a future banking crisis could be managed without extraordinary public intervention.
The Swiss government proposed requiring UBS to back its foreign subsidiaries with 100% Common Equity Tier 1 (CET1) capital.
The Swiss Parliament’s upper house subsequently supported a reduced threshold of 90%, compared with the current 60% requirement, which can partly be fulfilled with less costly forms of capital.
However, UBS considers even the revised proposal excessive.
In its September 23 statement, the bank estimated that the 90% requirement would necessitate approximately $16 billion in additional CET1 capital at UBS AG.
Including other regulatory requirements resulting from the Credit Suisse acquisition, UBS estimates cumulative incremental CET1 requirements of approximately $33 billion.
This is an enormous amount of capital that shareholders would otherwise prefer to see supporting international growth, investment, and distributions.
The dispute has now moved beyond technical banking regulation. It raises the possibility of Switzerland losing the headquarters of its largest financial institution.
Why Switzerland Insists on Stronger Rules
There is, however, an important counterargument.
The Swiss National Bank supports stronger capital backing of foreign subsidiaries, reasoning that losses abroad can undermine the financial stability of a parent bank at home.
From the government’s perspective, retaining a bank whose global balance sheet is exceptionally large relative to the Swiss economy creates a legitimate public-policy responsibility.
Switzerland must balance the interests of UBS shareholders against the interests of Swiss taxpayers.
The problem is that these two objectives are becoming increasingly difficult to reconcile.
Is London Preparing to Welcome UBS?
On October 16, the Financial Times reported that the British government had discussed the possibility of UBS relocating its headquarters and stock-market listing to London.
Former British Chancellor Rachel Reeves reportedly raised the possibility during discussions with UBS Chairman Colm Kelleher.
Reuters has separately reported that UBS is evaluating contingency scenarios involving relocation or a potential banking combination. The bank has not announced a decision to leave Switzerland, and no active merger negotiations were reported.
Nevertheless, London presents several compelling advantages.
First: An established financial ecosystem.
London remains one of the world’s leading international financial centres, with sophisticated infrastructure for wealth management, institutional custody, investment banking, foreign exchange, and cross-border financial services.
Second: A global banking workforce.
UBS already maintains a substantial British presence. Relocating its holding-company headquarters would not require building an entirely new international financial operation from scratch.
Third: Regulatory diversification.
A UK domicile could create an opportunity to reassess the group’s supervisory structure, capital allocation, and international operating model, subject to negotiations with British and Swiss regulators.
Fourth: Capital-market visibility.
A London headquarters and potentially a primary UK stock-market listing would represent a significant institutional victory for Britain.
However, relocation would not automatically exempt UBS’s Swiss banking operations from Swiss regulation. The legal, tax, capital, and resolution implications would be extensive.
Moving a global bank is considerably more complicated than relocating an ordinary multinational corporation.
The American Alternative: An Even Bigger Possibility
London is not the only destination under consideration.
Reuters reported on October 15–16 that UBS was examining several contingency scenarios, including potential combinations involving American banking institutions.
The United States is particularly attractive because UBS is pursuing further expansion of its American wealth-management franchise.
A US transaction could provide a strategic rationale for a broader corporate restructuring and potentially change the group’s international valuation profile.
Morgan Stanley has appeared in market commentary as a theoretical strategic match, partly because of the similarities between the two firms’ wealth-management ambitions.
But this remains speculation, not an announced transaction or evidence of merger negotiations.
An American move would introduce formidable regulatory, antitrust, political, and integration challenges.
For these reasons, London arguably offers a more straightforward European alternative, while the United States presents a potentially more transformative, but considerably more complicated, strategic route.
Invest Offshore Analysis: Three Possible Outcomes
Our assessment is that the coming months could produce one of three important outcomes.
Scenario One: Switzerland and UBS Reach a Compromise
This remains a credible near-term outcome.
Switzerland modifies its capital requirements sufficiently to retain UBS’s headquarters while maintaining stronger taxpayer protections.
UBS remains headquartered in Zurich, although the bank may continue shifting international functions toward other financial centres.
This would preserve the Swiss banking identity that remains such an important component of the institution’s global reputation.
Scenario Two: UBS Relocates Its Corporate Headquarters to London
If the Swiss legislative process produces a regulatory framework UBS considers economically unsustainable, London becomes an increasingly credible alternative.
Under this scenario, UBS could eventually establish its international holding-company headquarters in the United Kingdom while retaining substantial Swiss operations.
Switzerland would remain an important banking market, but it would no longer necessarily be the corporate centre of its most internationally significant financial institution.
Such an outcome could strengthen London’s position in international private banking and wealth management.
Scenario Three: UBS Pursues a Transformative International Combination
A transaction involving an international banking group, potentially including an American institution, could permanently alter UBS’s corporate structure.
This would be the most ambitious scenario, potentially creating an institution with an extraordinary combination of wealth management, institutional banking, custody, and international financial distribution.
It would also be the most difficult scenario to execute.
What Would a UBS Departure Mean for Swiss Private Banking?
There is an additional consideration that deserves attention from international investors and entrepreneurs.
UBS’s departure from Switzerland would not mean the end of Swiss private banking.
Quite the opposite: it could create opportunities for smaller, independently capitalized institutions.
Switzerland would retain its sophisticated financial infrastructure, private-banking expertise, established legal system, and international reputation.
But a significant institutional reorganization could create opportunities for specialist providers offering:
- Independent custody and fiduciary services.
- International private-banking relationships.
- Multi-currency treasury and settlement solutions.
- Specialist wealth and asset-management platforms.
- Regulated financial technology and banking infrastructure.
Such opportunities would depend on appropriate regulatory authorization, capital, institutional partnerships, and sound governance.
The wider question is whether international clients will increasingly seek diversified banking relationships instead of concentrating their financial affairs within a handful of systemically important institutions.
For Invest Offshore readers, this may be the most important long-term development.
The Dates to Watch
Two immediate dates could provide greater clarity.
October 26, 2026: A Swiss lower-house parliamentary committee is scheduled to begin considering the disputed banking regulations.
October 28, 2026: UBS is scheduled to publish its third-quarter financial results, providing another opportunity for investors to assess management’s outlook.
The broader parliamentary debate is expected to continue into December, with the possibility of further political or referendum-related uncertainty.
These developments should help determine whether relocation remains a negotiating contingency or becomes a serious corporate restructuring initiative.
Conclusion: Could Europe’s Next Banking Capital Be Decided in Bern?
The 2026 rankings show France’s dominance, HSBC’s strategic transformation, and Europe’s growing concentration of banking assets.
But the defining banking story of the coming year may not involve which institution has the largest balance sheet.
It may involve where one of Europe’s most influential banking groups chooses to establish its legal home.
Our editorial assessment is that UBS would prefer to preserve its Swiss identity if an economically acceptable regulatory settlement can be reached. However, London has emerged as a credible alternative, and shareholder pressure makes it increasingly difficult to dismiss relocation as an empty threat.
A departure is neither confirmed nor inevitable.
Yet something fundamental has changed: Switzerland’s largest bank is confronting the possibility that its international ambitions and domestic regulatory obligations may no longer fit comfortably within the same corporate structure.
For centuries, Swiss banking has attracted international capital.
The extraordinary question of 2026 is whether Switzerland’s most famous bank may now decide that its own capital is better headquartered somewhere else.
Research and references: The Global Banker — Europe’s Largest Banks 2026 | S&P Global Market Intelligence — Europe’s 50 Largest Banks | UBS September 23 Regulatory Statement | Reuters — UBS Exploring Options Abroad | Financial Times — UK Courted UBS Over London Move | Reuters — Swiss Capital Rules, October 19
Editorial note: The relocation scenarios represent Invest Offshore analysis based on publicly reported developments. No UBS headquarters relocation or merger has been formally announced.
Leave a Reply