
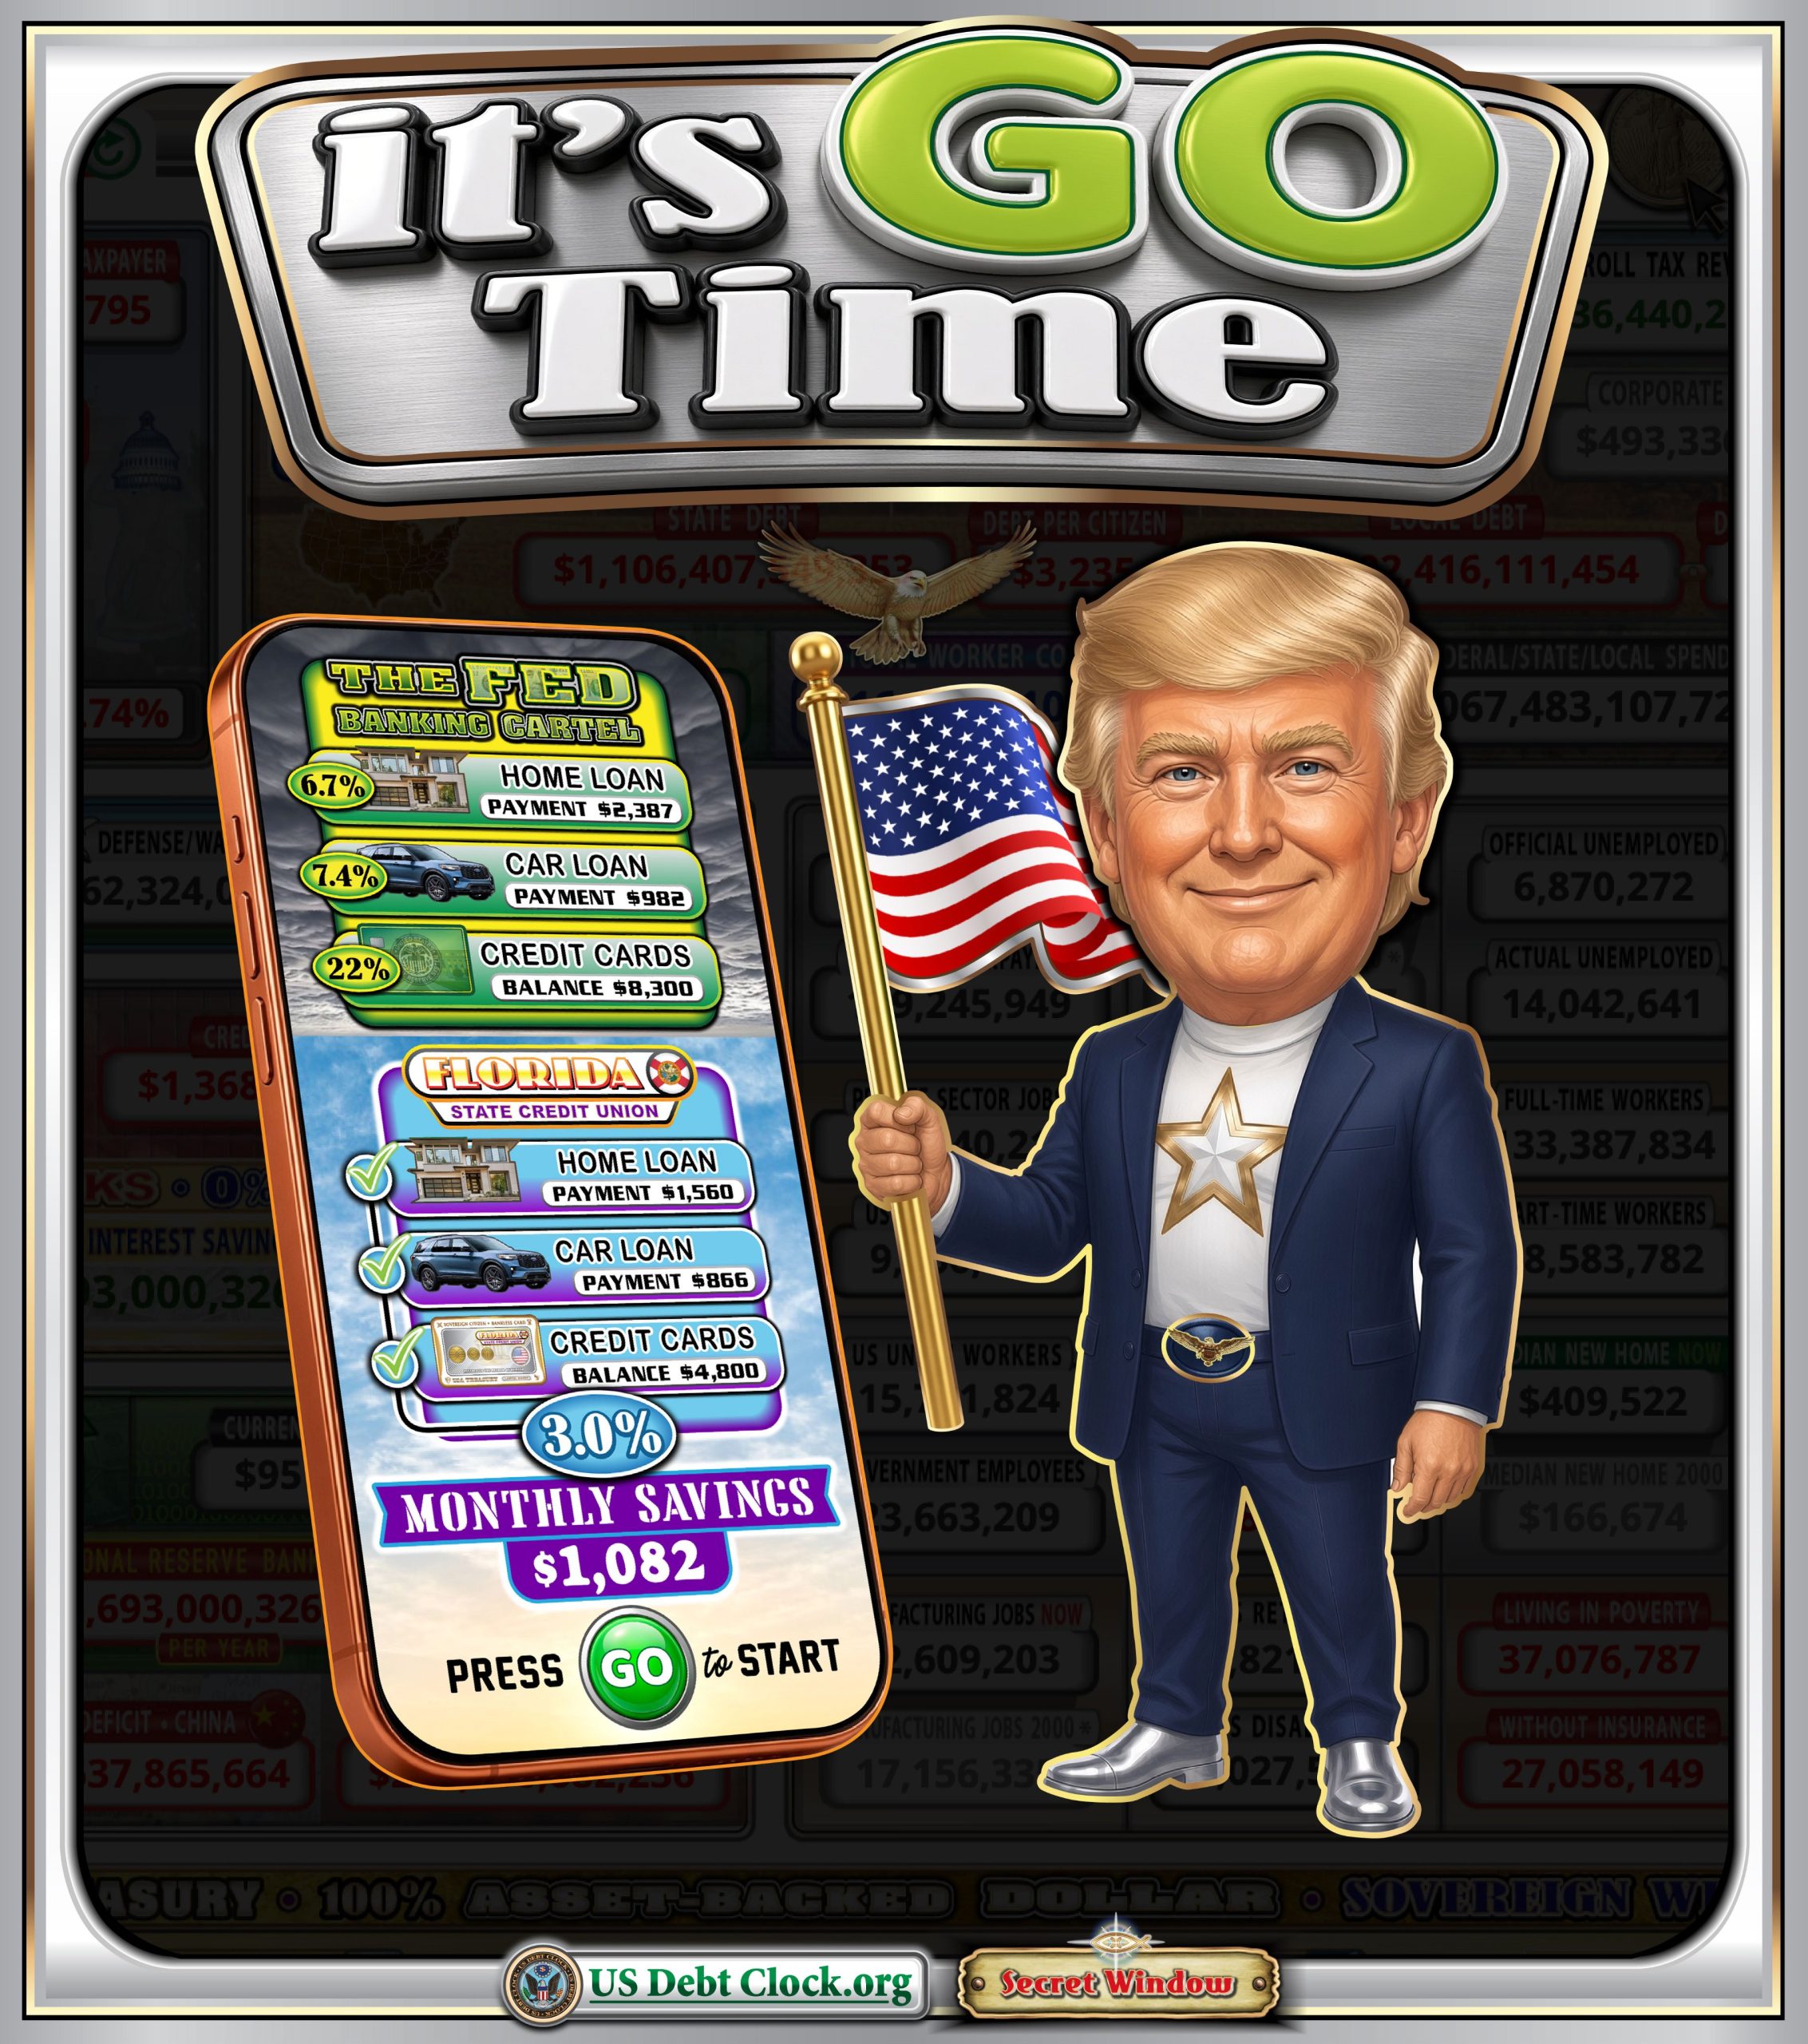
The US Debt Clock has released another “DJT” poster, and this one changes the tone again.
The headline is no longer theoretical.
It is not asking about cartel bankers, silver revaluation, Presidential Disclosure, or the mechanics of a seamless transition.
This one says:
It’s GO Time
And the message is aimed directly at the household level.
The poster shows DJT holding an American flag beside a smartphone. On the phone screen, the comparison is simple and visual:
The Fed Banking Cartel
Home loan: 6.7%
Car loan: 7.4%
Credit cards: 22%
versus
Florida State Credit Union
Home loan: lower payment
Car loan: lower payment
Credit cards: lower balance
3.0%
At the bottom, the poster highlights:
Monthly Savings: $1,082
Press GO to Start
That is the decode.
The US Debt Clock is no longer only selling the New Money Revolution as a patriotic, Treasury, gold, silver, or anti-Fed idea. It is now selling it as a household cash-flow revolution.
The Big Shift: From Monetary Theory to Monthly Savings
This poster is important because it takes a giant abstract idea — replacing the Fed debt-based dollar with a Treasury-centered credit system — and translates it into something every family understands:
How much money do I save each month?
That is the power of the image.
A new money system is hard to explain.
A 100% asset-backed Treasury Dollar is hard to visualize.
A sovereign wealth reserve is hard to make personal.
A banking cartel sounds distant.
But a mortgage payment, car payment, and credit card balance?
Everyone understands that.
The poster’s message is that the New Money Revolution becomes real when it reaches the kitchen table.
The 3% Credit Model
The phone screen is the heart of the poster.
It compares higher interest-rate debt under the old system with a proposed 3% state credit union model under the new system.
This connects directly to earlier US Debt Clock themes:
Banking as a utility
State credit union banks
3% maximum interest
Income tax deletion
Property tax removal
Treasury Dollar transition
An incentive-based society
The poster is saying that the old financial system extracts wealth through interest, while the new system would return wealth through lower debt service.
In plain terms:
Less interest means more monthly cash.
More monthly cash means more savings.
More savings means more investment.
More investment means more ownership.
More ownership means more freedom.
That is the “GO” button.
Why Florida Appears
The poster specifically names Florida State Credit Union as the example.
That detail matters because the Debt Clock has previously floated the idea of state-level credit systems as part of the New Money Revolution. In this storyline, states become practical delivery channels for lower-interest credit, while Treasury provides the broader monetary foundation.
The state becomes the retail interface.
Treasury provides the new money architecture.
State credit unions provide the household lending channel.
Citizens receive lower-rate loans.
The old banking spread gets squeezed.
That is the suggested model.
It is not presented as a normal bank advertisement. It is presented as a national pilot concept: start somewhere, show the savings, then scale.
“Press GO to Start”
The phrase “Press GO to Start” is brilliant because it makes monetary reform feel like an app.
That is the modern twist.
The old financial system is complex, slow, paperwork-heavy, fee-heavy, and bank-controlled. This poster makes the new system look simple, digital, and user-driven.
Open the phone.
Compare the rates.
See the savings.
Press GO.
The implication is that the new Treasury Dollar economy may not arrive as a speech or a ceremony. It may arrive as a practical financial interface: refinance, consolidate, save, and move.
That is why the smartphone matters.
The New Money Revolution is being framed not only as patriotic restoration, but as fintech deployment.
The Fed Banking Cartel vs. State Credit Union
The poster again uses the phrase Fed Banking Cartel, continuing the Debt Clock’s long-running critique of the Federal Reserve-era credit system.
In this image, the critique is not philosophical. It is mathematical.
The old system charges more.
The new system charges less.
That is the entire argument.
The Debt Clock is saying the fight against the old system will not be won merely by explaining 1913, banking history, monetary policy, or hidden interest extraction.
It will be won when citizens see the difference in their own monthly payments.
A lower mortgage payment is more persuasive than a white paper.
A lower car payment is more persuasive than a speech.
A lower credit card burden is more persuasive than a slogan.
That is why this poster may be one of the most effective in the series.
From “Start Small or Go Big” to “It’s GO Time”
This poster follows naturally from the earlier A Seamless Transition message.
That poster asked:
“When can we make the switch to the new Treasury Dollar?”
The answer was:
“We can start small or go big.”
Now the Debt Clock appears to be choosing the retail path:
Start with household credit.
That makes strategic sense inside the poster’s own narrative. Rather than asking the public to understand a full monetary reset all at once, the system could begin with something practical: lower-rate loans through a state-level credit union model.
The transition becomes real when citizens feel it.
The Invest Offshore Decode
For Invest Offshore readers, this poster is especially important because it connects macro-monetary reform to personal balance sheets.
The old system is about debt service.
The new system, according to the Debt Clock narrative, is about cash-flow liberation.
That has major implications for:
Real estate
Consumer credit
Private banking
Refinancing
Asset protection
State-level finance
Treasury-backed instruments
Digital settlement
Household capital formation
If families suddenly save hundreds or thousands per month through lower interest costs, that money does not disappear. It moves.
It moves into savings.
It moves into investments.
It moves into real estate.
It moves into business formation.
It moves into gold, silver, and digital assets.
It moves into the ownership economy.
That is why a monthly savings number matters.
It turns monetary reform into investable behavior.
The Bigger Message: Ownership Through Lower Friction
The US Debt Clock has repeatedly pointed toward an incentive-based society.
This poster shows what that could mean in daily life.
Lower interest removes friction.
Lower taxes remove friction.
Asset-backed money removes purchasing-power fear.
State credit unions remove dependence on cartel-style banking spreads.
Digital access removes unnecessary gatekeeping.
The result is not merely lower payments.
The result is a different kind of citizen.
Not just a taxpayer.
Not just a borrower.
Not just a consumer.
An owner.
That is the philosophical foundation behind the poster.
Reality Check
This poster should not be mistaken for official banking policy, tax law, or a live national refinancing program.
Americans still live under the current credit system. Loan rates, eligibility, underwriting, banking rules, tax obligations, and legal tender rules remain governed by existing institutions and law until formally changed.
But as a signal, this poster is powerful.
It tells us where the Debt Clock narrative is going next:
From abstract reset to practical benefit.
From national debt to household savings.
From Treasury theory to smartphone action.
From “someday” to “GO Time.”
Conclusion: The Revolution Reaches the Phone Screen
The US Debt Clock’s It’s GO Time poster may be one of the clearest messages yet in the New Money Revolution series.
It says the new system will not be judged only by gold reserves, Treasury seals, or anti-Fed language.
It will be judged by whether families actually save money.
A lower mortgage payment.
A lower car payment.
A lower credit card burden.
A monthly savings number people can see.
That is how a monetary revolution becomes personal.
The old system lives in debt service.
The new system, if it arrives, must prove itself in cash flow.
And according to the US Debt Clock, the next phase is no longer just theory.
It’s GO Time.
Leave a Reply